Rewards Cards
•
Oct 5, 2026
Cash Back Credit Cards Explained
Flat-rate vs tiered vs rotating cash back: how each structure earns, how redemption works, and how to estimate your real return.
A structured, issuer-neutral method for comparing credit card offers — define your goal first, then evaluate APR, fees, rewards, and eligibility against your own credit profile.
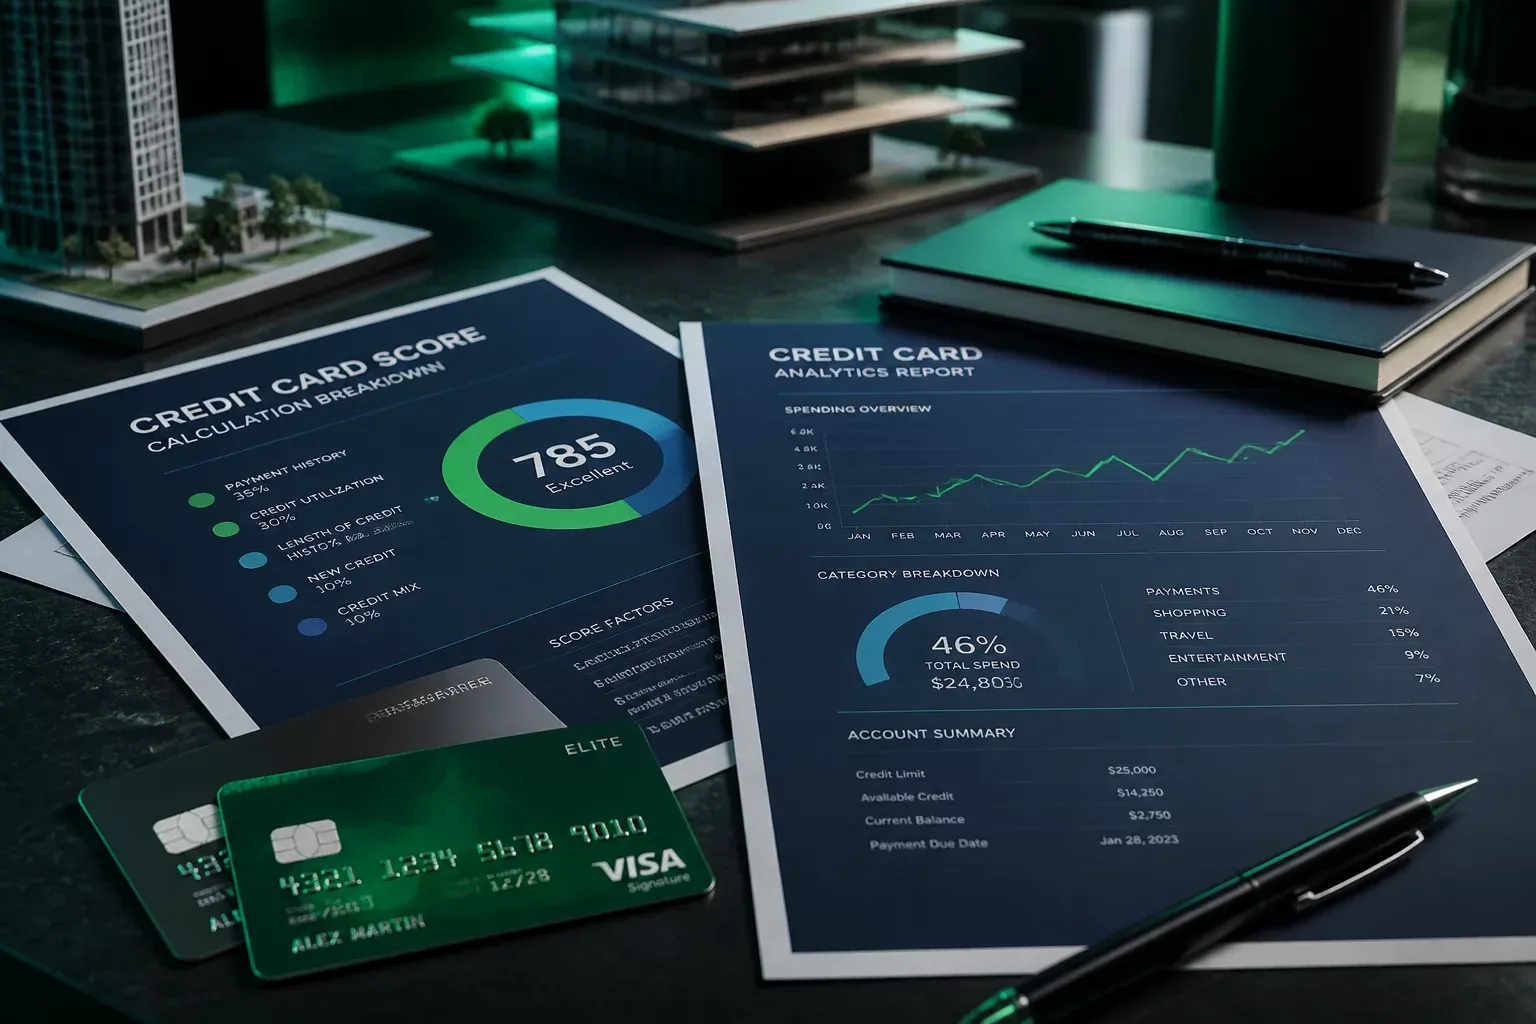
The U.S. market offers hundreds of consumer credit cards, and marketing language is designed to make each one look like the best. The correct choice is not universal — it depends on whether you carry a balance, what you buy, and where your credit score currently stands. A card ideal for a traveler who pays in full can be a costly mistake for someone paying down debt.
The disciplined approach is to work from your goal backward: choose the card category that matches your financial objective, then compare the standardized disclosures rather than headline rewards.
Start with your primary goal. If you will carry a balance, APR matters far more than rewards — no cash-back rate offsets double-digit interest. If you pay in full, compare reward structures against your actual spending categories. If you are building credit, look for products designed for limited history, such as student or secured cards.
Next, check your credit score to estimate which tier you realistically qualify for, and compare candidates through the Schumer box — the federally required table showing purchase APR, annual fee, penalty fees, and transaction fees in an identical format. Pre-qualification tools that use a soft inquiry let you gauge eligibility without affecting your score.
The CFPB requires issuers to present rates and fees in the standardized Schumer box so consumers can compare offers directly, and the CARD Act restricts how issuers can raise rates on existing balances. The FTC advises consumers to treat advertised 'pre-approved' offers as marketing rather than a guarantee of approval or final terms.
Funditia does not rank or endorse issuers. This framework is educational; verify all current terms in the official cardmember agreement and disclosure documents.
Educational references: Consumer Financial Protection Bureau (consumerfinance.gov) and Federal Trade Commission (consumer.ftc.gov). Funditia is an independent educational publication and is not a credit card issuer, lender, or credit repair organization.
Receive unbiased educational guides on credit cards, credit scores, and consumer protection rules based on CFPB and FTC public resources, directly to your inbox.
Flat-rate vs tiered vs rotating cash back: how each structure earns, how redemption works, and how to estimate your real return.
Points, miles, portals, and transfers — how travel cards earn and redeem rewards, and how to judge whether the annual fee is worth it.
Intro APR periods, transfer fees, and payoff math: when a balance transfer saves money and how to avoid the common traps.